How internal trade teams handle import and export risk and payment control
a[data-rs-seo-link]{text-decoration:underline!important;color:#1a56db!important;cursor:pointer!important;}a[data-rs-seo-link]{text-decoration:underline!important;color:#1a56db!important;cursor:pointer!important;}
Why internal handling matters in import and export
The phrase internal trade handle import and export points to a practical operating question: how should a company control cross-border orders before risk becomes delayed cargo, unpaid invoices or customs penalties? In most cases, the internal trade function should own the transaction file from quotation through cash collection. That does not mean replacing freight forwarders, customs brokers, banks or insurers. It means coordinating them through a defined workflow covering buyer and supplier checks, Incoterms, product classification, customs documents, payment terms, credit approval and shipment closeout.
This matters more when trade flows are volatile. The World Trade Organization’s October 2026 update said world merchandise trade volume growth for 2026 was revised upward to 3.9%, while the current dollar value of merchandise trade rose faster than volume in the first half of 2026. Faster growth can support exporters, but it also puts more pressure on finance, logistics and compliance teams. A clear internal process helps companies avoid treating every shipment as a separate emergency.
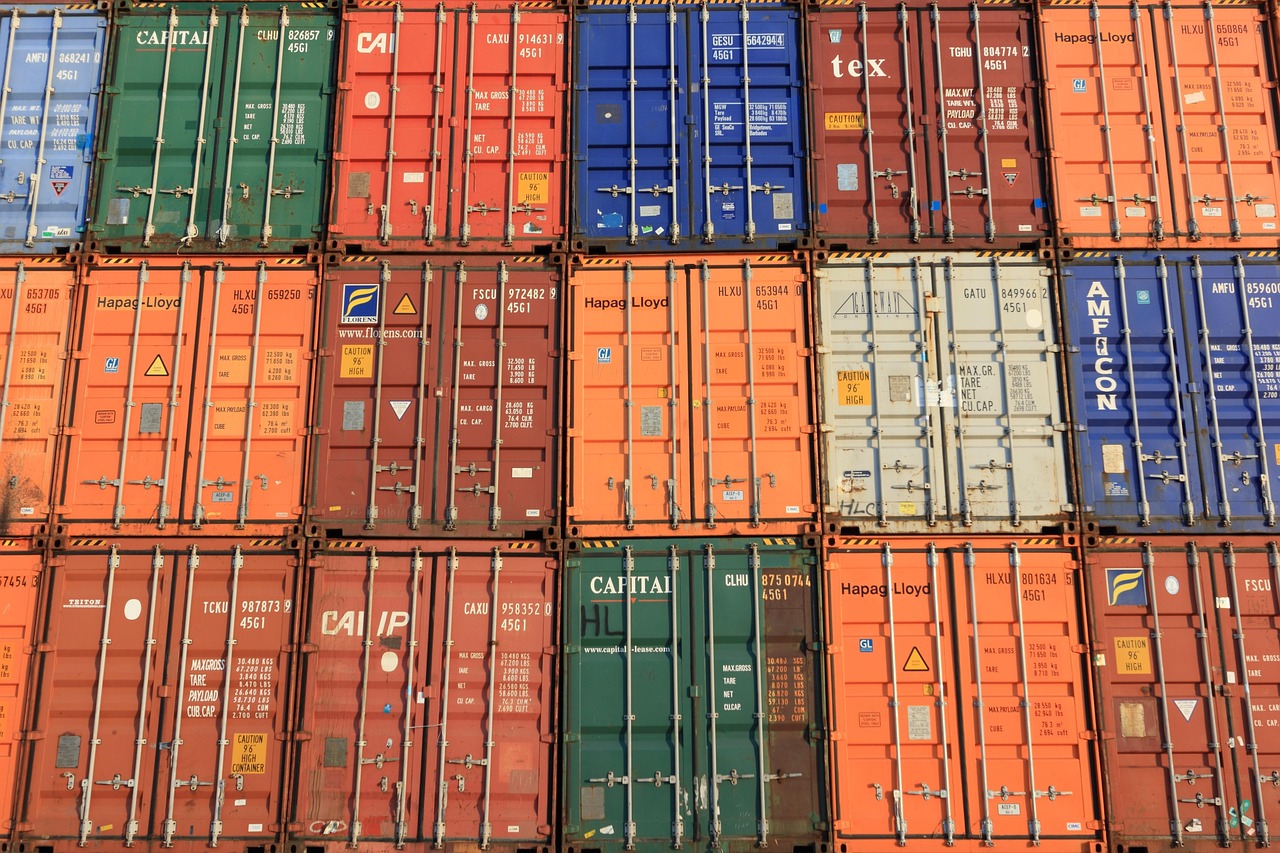
For more coverage of payment exposure, documentation and contract risk, see the site’s Trade Risk and Payment section.
Build the transaction map before the shipment moves
Import and export control should start before a purchase order is accepted. The internal team needs to map the transaction so that commercial promises are matched with operational duties. A sales team may agree to a short delivery window, a buyer may ask for open account terms, and a logistics provider may recommend a route. None of those decisions should be approved in isolation.
Contract and counterparty review
The first stage is counterparty review. For exports, this means checking the buyer, consignee, end user, destination country, bank and payment route. For imports, it means checking the supplier, country of origin, production capacity, quality obligations and any sanctions or forced-labor restrictions relevant to the goods. The aim is not only to reject high-risk deals. It is also to decide what controls are needed if the company proceeds.
The contract or purchase order should identify the product, quantity, currency, Incoterms rule, named place or port, required documents, inspection rights, delivery window, late-delivery consequences and payment trigger. If these points are vague, finance may not know when to pay, the broker may not have enough data for customs entry, and logistics may not know who bears the cost of delay.
Shipment and customs planning
The second stage is shipment planning. Internal trade staff should confirm the harmonized tariff classification, product description, origin information, valuation method, export license status where relevant, insurance requirement and packing details before cargo is booked. Correcting these items after departure can lead to amendments, demurrage, payment delays and disputes over who caused the problem.
Payment and closeout
The final stage is closeout. A transaction is not complete when the goods leave the seller’s warehouse. It closes when the documents match the contract, customs records are retained, payment is made or collected, claims are recorded, and lessons are fed back into the next shipment. Many companies lose visibility at this stage because logistics, finance and sales keep separate files. A central transaction record reduces that gap.
Use Incoterms as a control tool, not just a shipping abbreviation
Incoterms are often treated as three-letter labels, but they are risk allocation tools. The International Chamber of Commerce describes Incoterms 2020 as rules that allocate responsibilities, costs and risks between seller and buyer in business-to-business goods contracts. Internal trade teams should use them to prevent uncertainty, not simply copy terms from a previous invoice.
Each chosen rule should include a named place or port. “FOB Hamburg” is more useful than “FOB” because it identifies where the rule applies. “DAP buyer’s warehouse” and “CIP named destination” carry different cost, risk and insurance consequences. A term without a named place can create disagreement about delivery, freight charges and loss in transit.
Internal reviewers should also remember that Incoterms do not settle every legal issue. They do not by themselves determine title transfer, payment date, governing law, product quality, customs valuation or remedies for breach. Those points belong in the sales contract or purchase order. The distinction matters because payment disputes often arise when one party focuses on delivery under the shipping term while the other focuses on quality, missing documents or late arrival.
Common control questions include:
- Does the selected Incoterms rule fit the transport mode, especially for containerized cargo?
- Who arranges export clearance, import clearance, freight, insurance and unloading?
- At what point does risk transfer from seller to buyer?
- Does the payment trigger match the risk transfer point or the document presentation point?
- Can the company actually perform the customs or tax obligations implied by the term?
Match payment terms to risk, not habit
Payment terms should reflect counterparty risk, country risk, product risk, cash-flow needs and bargaining power. A long-standing customer may qualify for open account terms. A new buyer in a higher-risk market may require advance payment, a confirmed letter of credit or credit insurance. The internal trade team’s role is to recommend a term that matches the risk instead of allowing payment to become only a commercial concession.
| Payment method | Typical use | Main benefit | Main risk |
|---|---|---|---|
| Advance payment | High-risk buyer, customized goods or first transaction | Protects exporter cash flow before shipment | Buyer carries performance and delivery risk |
| Open account | Established buyer relationship and acceptable credit limit | Simple and commercially attractive | Exporter carries collection and late-payment risk |
| Documentary collection | Moderate trust where banks handle documents but do not guarantee payment | Lower bank cost than a letter of credit | Buyer may refuse documents or delay payment |
| Letter of credit | Higher-value or higher-risk cross-border sale | Bank payment depends on complying documents | Document discrepancies can delay or block payment |
| Standby letter of credit or guarantee | Backstop for non-payment or performance failure | Provides a secondary claim if the applicant defaults | Requires precise wording and careful expiry control |
The ICC Trade Register has repeatedly characterized short-tenor trade finance as a relatively low-risk asset class for banks, and its 2025 materials refer to a large dataset of bank-submitted trade finance transactions. That does not mean every individual shipment is low risk for the exporter or importer. The company still needs document discipline, credit limits and clear escalation rules. A bank may be comfortable with the instrument while the trading company still faces margin loss, storage cost, product rejection or currency exposure.
A useful internal policy separates payment approval from sales enthusiasm. Sales can request open account terms, but finance should approve credit limits, treasury should review currency exposure, compliance should screen restricted parties, and operations should confirm that document requirements are realistic. The more complex the payment method, the earlier it should be reviewed.
Control documents and data as carefully as the goods
In import and export trade, documents are not paperwork after the fact. They are part of the product being delivered. Customs authorities, banks, insurers, carriers and buyers rely on documents to determine what the goods are, where they came from, who owns or controls them, how they should be treated and whether payment conditions have been met. See also: Customs and Compliance.
A standard export file may include a commercial invoice, packing list, transport document, export declaration, certificate of origin where required, insurance certificate, inspection certificate, license or permit where applicable, and any bank-specific documents required by the payment method. An import file may include supplier invoice, packing list, bill of lading or air waybill, customs entry, duty calculation, origin support, proof of payment, broker instructions and delivery records.
For letters of credit, the document standard is especially strict. Under UCP 600, banks examine documents rather than the physical goods, and banks have a maximum of five banking days after presentation to determine whether a presentation complies. This makes internal review essential. A shipment can be physically correct but financially delayed if the invoice, transport document and certificate data conflict.
Internal teams should maintain a document checklist by product and route, not only by customer. The checklist should identify mandatory fields, responsible owners and deadlines. It should also distinguish between commercial documents, customs documents, transport documents and bank documents. This helps prevent a common problem: a document may satisfy the buyer but fail customs requirements, or satisfy customs but fail the bank’s credit terms.
Assign clear internal owners for trade risk
Many import and export failures are not caused by lack of expertise. They are caused by unclear ownership. A broker may expect the importer to provide correct classification. Finance may expect logistics to confirm delivery. Sales may expect the buyer to arrange import clearance. These assumptions create gaps. A simple responsibility matrix can reduce them.
| Function | Core responsibility | Key control question |
|---|---|---|
| Sales or procurement | Commercial terms, customer or supplier communication and order accuracy | Are contract terms aligned with operational capability? |
| Trade compliance | Classification, origin, sanctions screening, license review and recordkeeping | Can the shipment legally move as planned? |
| Logistics | Carrier booking, routing, insurance coordination and delivery visibility | Does the route match the contract and risk profile? |
| Finance and treasury | Credit limits, payment terms, bank instruments, currency and cash flow | Does the payment structure protect the company’s exposure? |
| Tax and customs | Duties, VAT or GST, valuation and import accounting | Are landed cost and tax obligations understood before shipment? |
| Legal | Contract wording, dispute resolution, guarantees and exceptional risk clauses | Are rights and remedies clear if the transaction fails? |
The matrix does not need to be complex. It needs to be used before commitment. If the company agrees to Delivered Duty Paid terms, for example, someone must confirm whether it can act as importer of record in the destination market and whether tax registration or local representation is needed. If nobody owns that question, the term may look attractive commercially but fail operationally.
A practical checklist for import and export control
A strong internal workflow is easier to maintain when it is reduced to repeatable checkpoints. The checklist below can be adapted for both importers and exporters.
- Confirm the legal parties, buyer, seller, consignee, end user and banks involved in the transaction.
- Screen counterparties, destination, origin, vessel or carrier where relevant, and goods against applicable sanctions and restricted-party requirements.
- Verify product classification, export control status, origin and customs valuation support before shipment.
- Choose an Incoterms 2020 rule with a specific named place or port and confirm who handles export and import clearance.
- Set payment terms based on credit risk, country risk, order value, product customization and cash-flow impact.
- Prepare a document list that matches the contract, customs rules, transport mode and bank requirements.
- Confirm insurance coverage and responsibility for loss, damage, delay, storage and demurrage.
- Record approvals for exceptions, such as open account terms for a new customer or shipment before license confirmation.
- Track shipment milestones against payment triggers and document deadlines.
- Close the file only after payment, customs record retention and any claims or discrepancies are resolved.
The checklist should not be treated as a one-time compliance exercise. It should become a feedback loop. Repeated document discrepancies, customs holds, buyer payment delays or supplier quality disputes should change future credit limits, approved routes, document templates or contract clauses.
Frequently asked questions
Should import and export control sit in finance, logistics or compliance?
There is no single structure that fits every company. Smaller companies may place the function under finance or operations, while larger companies may have a dedicated global trade team. What matters is that one internal owner coordinates finance, logistics, sales, customs and compliance decisions before the shipment moves.
Is a letter of credit always safer than open account terms?
No. A letter of credit can reduce buyer non-payment risk if documents comply, but it adds cost and document complexity. Open account terms may be reasonable for a strong, established buyer with an approved credit limit. The safer choice depends on counterparty risk, documentation capability, transaction value and the company’s cash-flow position.
Why do document discrepancies cause payment delays?
Bank payment under a documentary credit depends on documents, not on a general belief that the goods are acceptable. If invoice data, transport details, dates, product descriptions or required certificates conflict with the credit terms, the bank may treat the presentation as discrepant. Internal pre-checks reduce this risk.
How often should internal trade procedures be reviewed?
Procedures should be reviewed when entering a new market, adding a new product, changing Incoterms, using a new bank instrument, changing brokers or experiencing repeated delays. A scheduled annual review is useful, but event-based reviews are more important when risk changes quickly.
What is the biggest mistake companies make in handling import and export internally?
The biggest mistake is separating the commercial deal from payment, customs and logistics realities. A profitable order can become a loss if the company accepts unclear delivery terms, weak payment protection, incomplete customs data or document requirements it cannot meet on time.